On this page
What you need to know now
A payment sent against the wrong tax reference needs a documented correction request. Do not assume an old email address is still the correct submission channel.
The original article is preserved below as a historical record. Earlier deadlines, rates, offers and approval statements should not be used as current guidance.
- Retain bank proof and the payment reference.
- Identify the intended and credited tax accounts.
- Check the receiving account’s authority and consent requirements.
Establish exactly where the payment went
Start with the payment itself, rather than assuming that a bank debit proves the intended tax account received the money. Record the payment date, amount, currency, bank transaction reference and tax reference entered. Compare that information with the receipt and the statement visible in the relevant EmaraTax account. An incorrect reference, a payment still being processed and an amount credited against another tax account require different explanations to support staff.
Prepare a clear correction file
Keep the original bank confirmation and a short chronology showing who initiated the transfer, which liability it was intended to settle and how the mistake was discovered. Identify both the intended registration number and the number used. Where another legal person is involved, establish who can authorise disclosure or a correction request. Avoid changing the underlying bank evidence; explain discrepancies in a separate note so the original transaction remains traceable.
Use the current official support route
The old email instructions in the original article describe a past procedure. Obtain current instructions through the FTA service or verified support channel before submitting identity or banking information. Present one consistent request, attach the required evidence and retain its reference. If further documents are requested, connect the response to that case rather than sending several unrelated requests that leave the same payment appearing to be multiple separate issues.
Confirm the account outcome
A request acknowledgement is different from confirmation that a liability has been settled. Check the receiving account after the case is resolved and reconcile the corrected entry with the bank payment and liability. Retain the FTA response with the accounting records. Do not assume that transferring a payment automatically removes a late-payment charge: ask for the applicable treatment to be confirmed and keep any separate penalty review or decision with the case. For internal control, have a second person compare the tax reference on a future payment instruction with the approved liability before the bank transfer is released.
YOUR NEXT STEPS
A practical way forward
- 01
Step 1
Build a clear payment chronology.
- 02
Step 2
Prepare the bank evidence and account details.
- 03
Step 3
Obtain current instructions from the FTA and track the correction.
CLEAR ANSWERS
Frequently asked questions
Does sending an email guarantee transfer or penalty waiver?
No.
Should passwords or PINs be sent with the request?
No. Provide only the evidence required through a verified official channel.
Read the original article First published 3 August 2021 · retained for context
This earlier article is preserved for context. Its rates, deadlines, approvals and announcements may have been superseded. Use the current guidance and official references on this page for your next step.
Learn about the learn about the requirements for transferring wrongly paid amounts to the correct registration numbers.
Transferring wrongly paid amounts : A letter of no objection signed by the authorised signatory who received the amount paid by mistake, on the company letterhead, with the following details:
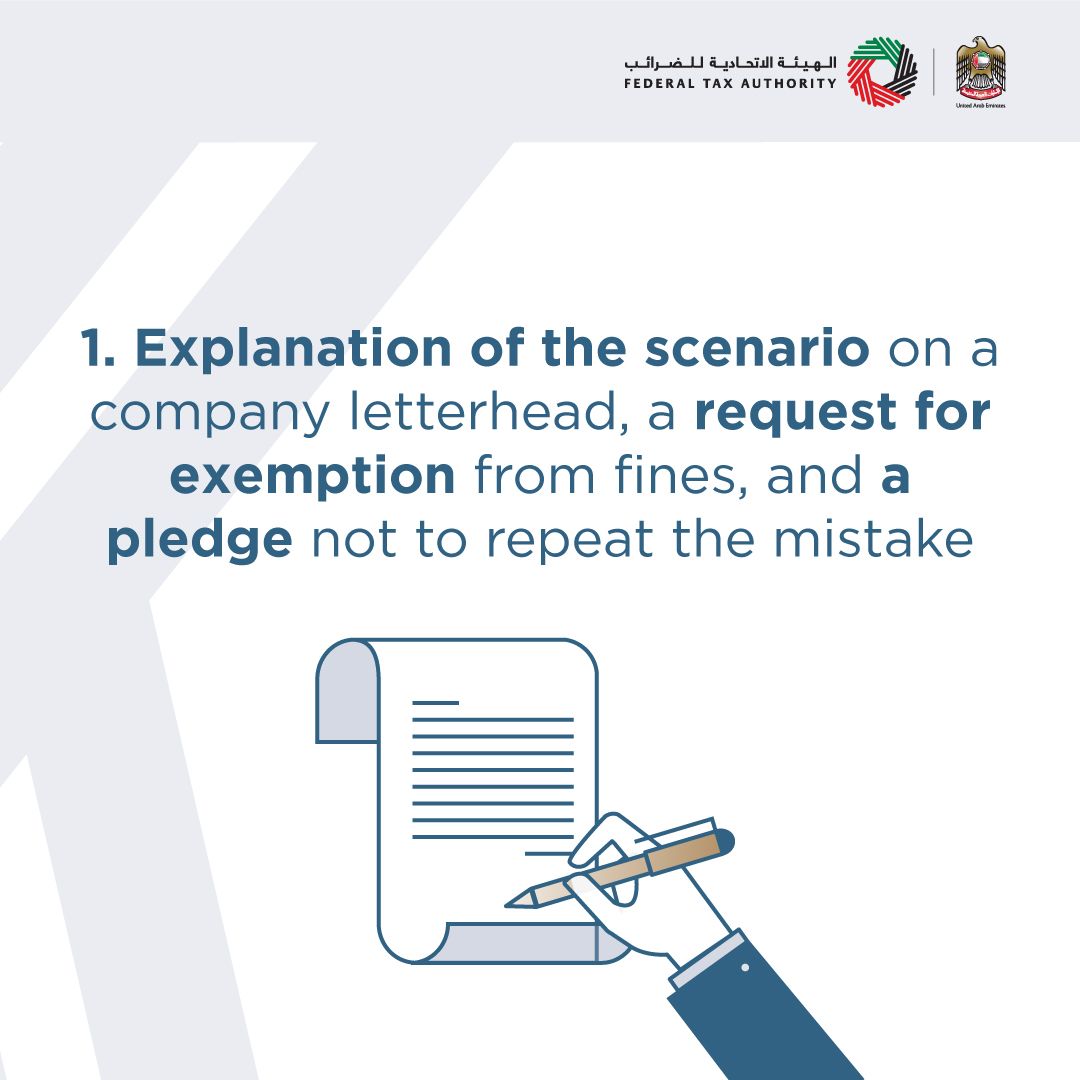
- Explanation of the scenario on a company letterhead, a request for exemption from fines, and a pledge not to repeat the mistake
- The correct tax registration number to be paid and the wrong tax registration number.
- Amount paid, tax period, date of payment, copy of transfer or account statement
- A letter of no objection signed by the authorised signatory who received the amount paid by mistake containing the company letterhead with the following details:
- The amount Received
- Wrong TRN
- The Correct TRN to which the amount should be transferred
- Send all documents to payment.transfer@tax.gov.ae
VERIFY THE DETAIL
Official sources & further reading
Source checks support this general guide. Your treatment depends on the facts, tax period and applicable legislation.