
On this page
What you need to know now
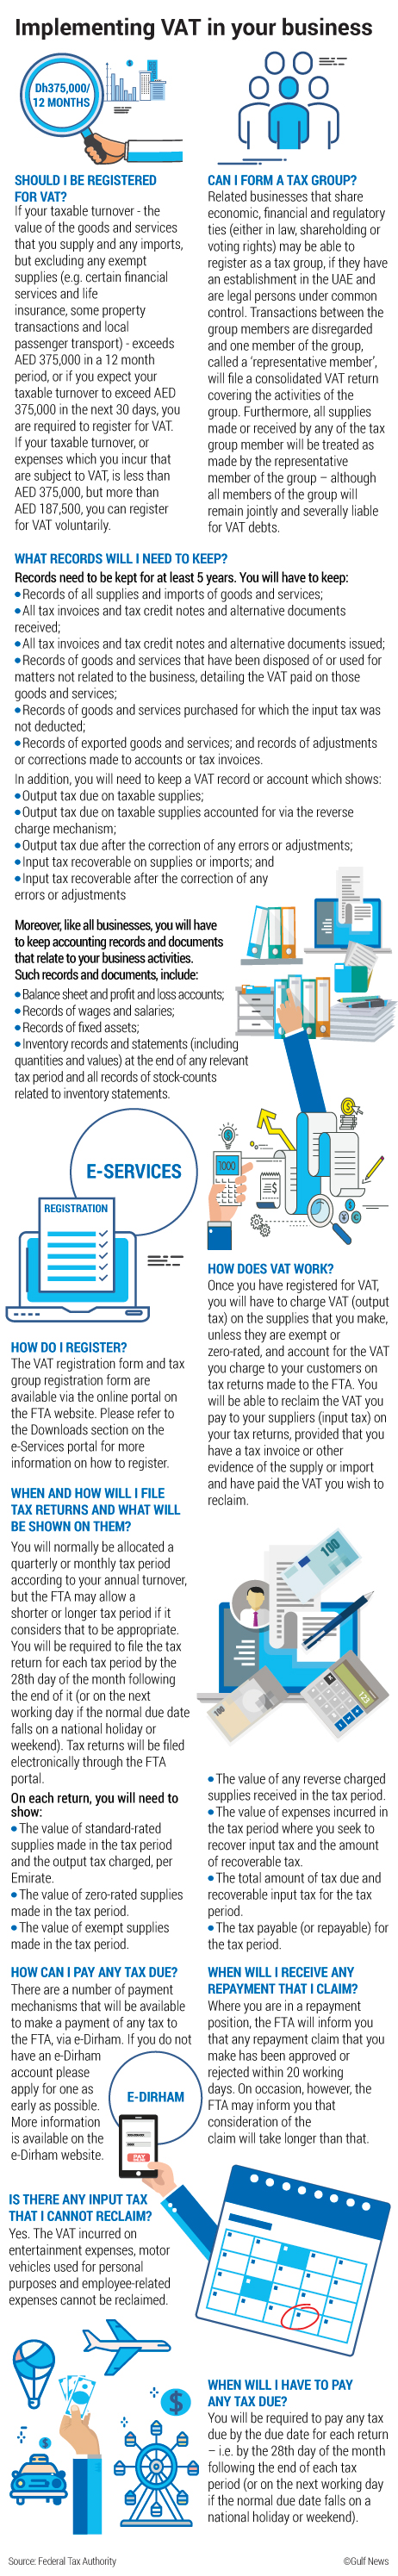
For a UAE-resident business, mandatory VAT registration generally applies when taxable supplies and imports exceed AED 375,000 in the previous 12 months or are expected to exceed it in the next 30 days. Voluntary registration can be available above AED 187,500, including qualifying taxable expenses.
- Identify the correct taxable person.
- Separate exempt sales from taxable supplies.
- Retain the calculation and supporting records.
Calculate the threshold using the correct activity
For a UAE-resident business, the registration assessment generally compares taxable supplies and imports with the mandatory threshold over the relevant previous and expected periods. Voluntary registration has its own test, including qualifying taxable expenses. Profit is not the measure, and exempt income should not simply be treated as taxable turnover.
Build a monthly calculation from transaction reports and explain material adjustments. A spreadsheet that shows only one annual total may hide when a threshold was crossed. Keep the supporting reports and the reason for including or excluding unusual items so that the conclusion can be reviewed rather than guessed later.
Check the legal identity and non-resident position
A company, a branch and a sole establishment are not interchangeable descriptions. Identify the person carrying on the activity before deciding what belongs in the calculation. Multiple licences do not always create multiple taxable persons, while common ownership does not automatically merge separate companies.
Non-resident businesses also require a distinct assessment. The resident threshold should not be applied mechanically to a foreign supplier. Consider the supplies made in the UAE and whether another person accounts for the relevant tax. Obtain a transaction-specific review where the business model crosses borders or involves several contracting entities.
Prepare an evidence-led application
Match the application to the applicant’s legal form and facts. Useful records include licences, incorporation information, authorised-signatory evidence and a supported turnover declaration. Where future activity is relevant, contracts and purchase orders should explain the expectation rather than a forecast with no commercial basis.
Check consistency before submission: names, dates, activities and figures should agree across the profile and attachments. If a record is unavailable, identify the issue early. Retain the submitted version and any subsequent information requests so that the final approval can be connected to the evidence actually provided.
Decide how the registration will be maintained
A registration project should include an operating plan for the period after approval. Confirm the effective date and review how invoices, customer records and accounting codes will be updated. Establish a filing calendar and the evidence required from sales, purchasing and logistics.
Reassess the position when the business changes. Adding exempt activity, a new branch or a different import arrangement can affect more than the information displayed on the certificate. Periodic review helps the business identify required account updates and maintain a consistent basis for returns, instead of treating registration as a document obtained once and then forgotten.
YOUR NEXT STEPS
A practical way forward
- 01
Step 1
Compile the relevant turnover and import data.
- 02
Step 2
Assess registration and prepare the evidence.
- 03
Step 3
Submit through the current FTA route and retain the decision.
CLEAR ANSWERS
Frequently asked questions
Does profit determine the VAT threshold?
No. VAT registration uses the relevant supply and import measures.
Does a free zone licence itself remove VAT registration?
No. Assess the actual supplies and rules.
Earlier article & background First published 7 December 2017 · retained for context
This earlier article is preserved for context. Its rates, deadlines, approvals and announcements may have been superseded. Use the current guidance and official references on this page for your next step.
With the release of the executive regulations last week, we now have more details on the registration process
Dubai: According to the executive regulations on value added tax (VAT) published last week, the mandatory registration threshold is Dh375,000.
This means that anyone with a turnover of Dh375,000 or more is required to register their business for VAT, the Federal Tax Authority (FTA) and Ministry of Finance (MoF) said in the recently release regulations.
The voluntary registration threshold is Dh187,500, with companies of that size or above able to register for VAT too.
The failure of a taxable person or business to submit a registration application within the time frame specified in the tax law is liable for a Dh20,000 fine.
Also according to the executive regulations, companies are able to register as a tax group.
Through this mechanism, more than one company can register for VAT as a group, under a single common control, according to Dubai-based Jitendra Consulting Group. They say that the main benefit of group registration is to simplify the procedures and save costs through consolidated tax returns and a single VAT registration.
The group’s tax returns and payments are carried out by the member who acts as a representative of the group, the FTA has stated. All the members are jointly liable, however.
VERIFY THE DETAIL
Official sources & further reading
Source checks support this general guide. Your treatment depends on the facts, tax period and applicable legislation.


